| 63.05 -0.59 (-0.93%) | 10-30 16:00 | |||||||||||||
|
|
| Short term |   |
|||
| Mid term |  |
|||
| Targets | 6-month : | 75.1 | 1-year : | 87.71 |
| Resists | First : | 64.3 | Second : | 75.1 |
| Pivot price | 62.66  |
|||
| Supports | First : | 61.62 | Second : | 59.97 |
| MAs | MA(5) : | 63.35 |
MA(20) : | 62.37 |
| MA(100) : | 60.78 |
MA(250) : | 53.08 |
|
| MACD | MACD : | 0.4 |
Signal : | 0.3 |
| %K %D | K(14,3) : | 72.4 |
D(3) : | 74.2 |
| RSI | RSI(14): 55 |
|||
| 52-week | High : | 64.3 | Low : | 39.62 |
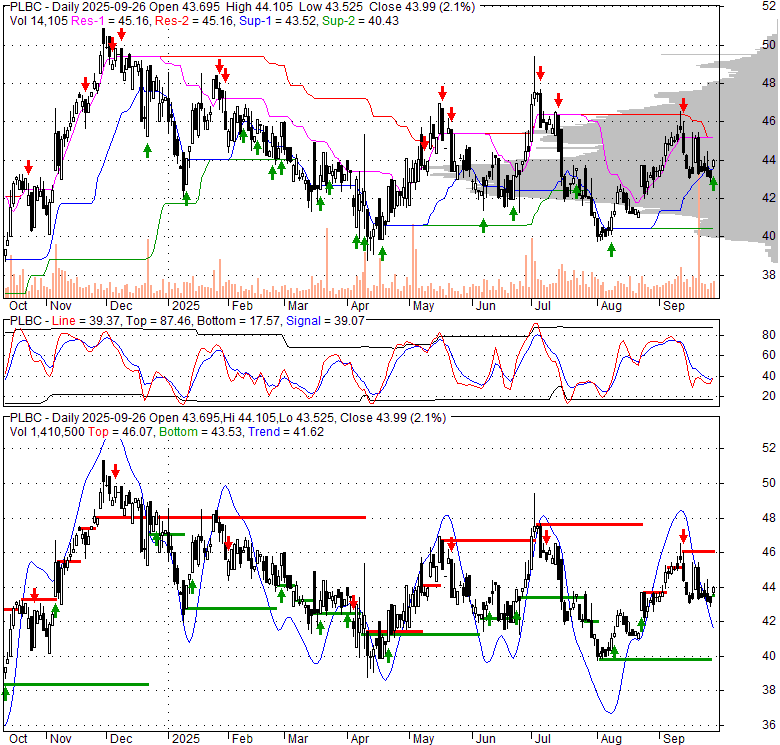
Price has closed below its short-term moving average. Short-term moving average is currently above mid-term; and above long-term moving average. From the relationship between price and moving averages: This stock is NEUTRAL in short-term; and BULLISH in mid-long term.[ PLBC ] has closed below upper band by 37.0%. Bollinger Bands are 13.8% narrower than normal. The current width of the bands does not suggest anything about the future direction or movement of prices.
| If tomorrow: | Open lower | Open higher |
| High: | 63.85 - 64.16 | 64.16 - 64.46 |
| Low: | 61.93 - 62.32 | 62.32 - 62.71 |
| Close: | 62.32 - 62.95 | 62.95 - 63.56 |
Plumas Bancorp functions as the parent holding company for Plumas Bank, a financial institution that delivers a broad spectrum of banking products and services. Its clientele primarily consists of individuals, as well as small and mid-sized businesses, situated across Northeastern California and Northwestern Nevada. The bank's diverse deposit offerings include conventional checking, money market checking, specialized business and public funds sweep accounts, savings, time deposits, and various retirement accounts. On the lending side, Plumas Bank provides a comprehensive suite of options, such as term loans for real estate, commercial endeavors, and industrial operations; government-guaranteed and agricultural financing; revolving lines of credit; consumer loans like auto and home equity; funding for land development and construction projects; and Small Business Administration (SBA) loans. Beyond its core deposit and lending products, the company extends modern conveniences like remote deposit, telephone and mobile banking, and internet banking complete with bill-pay functionality. Additional services encompass cashier's checks, mail-in banking, automated teller machines (ATMs), night depositories, safe deposit boxes, direct deposit, electronic funds transfers, and other standard banking facilities. As of February 28, 2022, Plumas Bank operated through 14 full-service branches and 3 dedicated lending offices. Incorporated in 1980, Plumas Bancorp maintains its corporate headquarters in Reno, Nevada.
Fri, 23 Oct 2026
Plumas Bancorp Estimates – NASDAQ:PLBC - TradingView
Thu, 22 Oct 2026
Plumas Bancorp (PLBC) Declares $0.33 Quarterly Dividend; 2.1% Yield - StreetInsider
Thu, 22 Oct 2026
PLUMAS BANCORP DECLARES QUARTERLY CASH DIVIDEND - GlobeNewswire
Thu, 22 Oct 2026
Plumas Bancorp (PLBC) Stock Stays Calm After Strong Q3 Earnings - Simply Wall St
Thu, 22 Oct 2026
Plumas Bank's CFO will retire Jan. 1, 2027, then stay on as a special assistant. - Stock Titan
Thu, 22 Oct 2026
Plumas Bancorp (PLBC) Q3 Earnings Power Quietly Builds Beneath Calm Stock Reaction - Yahoo Finance
| Price to Book Value: P/BV, a ratio used to compare book value to its current market price, to gauge whether a stock is valued properly. |
Underperform |
| Price to Earnings: PE, the ratio for valuing a company that measures its current share price relative to its earnings per share (EPS). |
Neutral |
| Discounted cash flow: DCF, a valuation method used to estimate the value of an investment based on its expected future cash flows. |
Outperform |
| Return on Assets: ROA, indicates how profitable a company is in relation to its total assets, how efficiently uses assets to generate a profit. |
Outperform |
| Return on Equity: ROE, a measure of financial performance calculated by dividing net income by equity. a gauge of profitability and efficiency. |
Outperform |
| Debt to Equity: evaluate financial leverage, reflects the ability of equity to cover outstanding debts in the event of a business downturn. |
Neutral |
|
Exchange:
NASDAQ
|
|
|
Sector:
Financial Services
|
|
|
Industry:
Banks - Regional
|
|
| Shares Out | 7 (M) |
| Shares Float | 6 (M) |
| Held by Insiders | 6.4 (%) |
| Held by Institutions | 53.2 (%) |
| Shares Short | 326 (K) |
| Shares Short P.Month | 258 (K) |
| EPS | 6 |
| EPS Est Next Qtrly | 0 |
| EPS Est This Year | 0 |
| EPS Est Next Year | 0 |
| Book Value (p.s.) | 37.79 |
| Profit Margin | 36.9 % |
| Operating Margin | 50.8 % |
| Return on Assets (ttm) | 1.8 % |
| Return on Equity (ttm) | 16.5 % |
| Qtrly Rev. Growth | 6.5 % |
| Gross Profit (p.s.) | 16.42 |
| Sales Per Share | 16.42 |
| EBITDA (p.s.) | 0 |
| Qtrly Earnings Growth | 120.5 % |
| Operating Cash Flow | 0 (M) |
| Levered Free Cash Flow | 0 (M) |
| PE Ratio | 10.5 |
| PEG Ratio | 1.4 |
| Price to Book value | 1.66 |
| Price to Sales | 3.83 |
| Price to Cash Flow | 0 |
| Dividend | 0.33 |
| Forward Dividend | 0 |
| Dividend Yield | 0.5% |
| Dividend Pay Date | Invalid DateTime. |
| Ex-Dividend Date | Invalid DateTime. |
|
|
|
|
|
|
|
|
|